Do I Have to Pay Tax on Money I Bring Into Canada?
One of the biggest anxieties many of us face when planning our move to Canada, or even after landing, is the lingering question of money. Specifically, people often worry, "Do I have to pay tax on money I bring into Canada?" It's a completely valid concern, filled with myths and half-truths that can make your head spin. Let's unravel this financial puzzle together, cut through the jargon, and understand what Canada's tax system really means for your hard-earned funds from abroad.
The Core Question: Tax on Money Brought Into Canada?
Let's get straight to it, because this is often the source of so much confusion: Canada generally does not tax the capital you bring into the country. What does that mean? It means if you sold your house back home, or you've been diligently saving up your entire life, the actual lump sum of money you transfer or carry with you when you establish residency here is typically not considered taxable income by the Canada Revenue Agency (CRA). This is a huge sigh of relief for many, and it’s important to understand the nuance.
Understanding Initial Capital vs. Income
This distinction is absolutely crucial. Think of it this way: the money you had before you became a Canadian tax resident is your capital. It's like your personal net worth that you're simply relocating from one country to another. The Canadian tax system is designed to tax income earned while you are a tax resident of Canada, not the wealth you already possessed before you arrived.
For instance, let's say you sold a property in your home country a month before you moved to Toronto, and you're bringing those proceeds over to buy a new home or simply settle your family. That money, being the proceeds of a sale that occurred before you established tax residency in Canada, is generally not taxed when it enters your Canadian bank account. The same applies to your personal savings, a pension lump sum from prior employment abroad, or funds from a business sale that was completed before your move. These are considered capital, not new income earned within the Canadian tax system. The key here is the timing: was the money earned while you were a Canadian tax resident, or was it already yours as capital before that point?
Declaring Funds at the Border
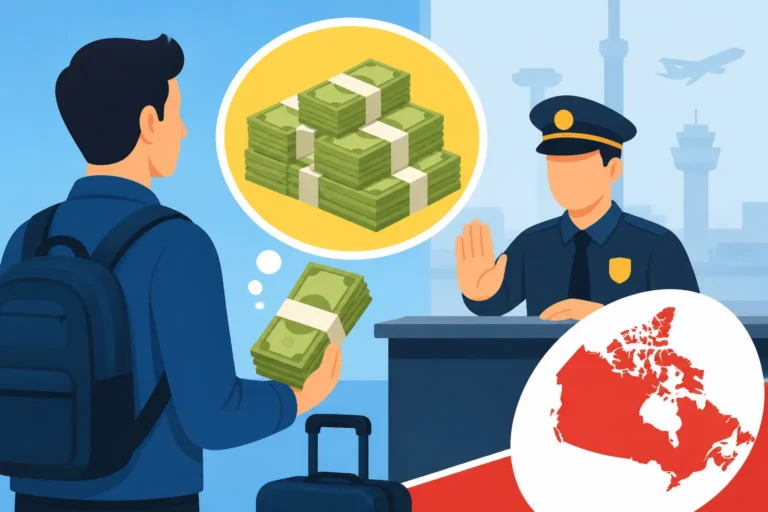
While Canada doesn't tax your initial capital, there's a very important administrative step you must adhere to: declaring large sums of cash or monetary instruments at the border. If you are entering Canada with CAD $10,000 or more in cash or monetary instruments (which can include things like stocks, bonds, cheques, or money orders), you are legally required to declare it to the Canada Border Services Agency (CBSA) upon arrival.
This isn't about taxation. The CBSA isn't looking to slap a tax on your savings. This declaration requirement is part of Canada's efforts to combat money laundering, terrorist financing, and other illegal activities. They want to know where large sums of money are coming from and going. It’s a standard procedure in many countries worldwide. Failing to declare these funds can lead to serious consequences, including fines, seizure of the money, or even arrest. You definitely don't want to start your new Canadian life with that kind of headache. So, if you're carrying a significant amount, just be honest and upfront with the border services officer. It's a simple process, and it keeps you on the right side of the law.
Tax Residency: The Crucial Concept
Understanding tax residency in Canada is perhaps the most critical piece of this puzzle. It's not about your citizenship or your immigration status; it's about where Canada considers you to have established sufficient ties to be responsible for paying taxes on your worldwide income. This concept dictates when your tax obligations to Canada truly begin and what income you need to report.
De Facto vs. Non-Resident Status
When it comes to Canadian tax law, you’re generally considered a factual resident (or "de facto resident") if you establish significant residential ties in Canada. This means Canada becomes your habitual abode. Conversely, you're a non-resident if you don't have these ties or if you've severed them upon leaving the country.
The CRA looks at a combination of "residential ties" to determine your status. These ties aren't just about where you sleep. They include:
- A home in Canada: Do you own a property or have a long-term lease?
- A spouse or common-law partner in Canada: Is your family here with you?
- Dependants (children) in Canada: Are your children attending school here?
- Personal property in Canada: Do you have furniture, cars, or other personal belongings?
- Social ties in Canada: Are you part of clubs, religious organizations, or have professional memberships?
- Economic ties in Canada: Do you have Canadian bank accounts, credit cards, investments, or a job?
- Canadian driver's license and passport: These are also indicators.
It's a holistic assessment. For instance, if you arrive in Vancouver with your family, rent an apartment, enroll your kids in school, get a job, and open bank accounts, you're pretty clearly a factual resident from the day you land. For a deep dive into this, you'll want to read up on Understanding Tax Residency Rules and Residential Ties in Canada. This concept truly underpins all your tax obligations in Canada.
When Does Your Tax Residency Begin?
For most newcomers, your tax residency in Canada begins the day you arrive and establish significant residential ties. It's not necessarily tied to when you get your Social Insurance Number (SIN) or even your provincial health card, although these are certainly indicators of establishing those ties.
Let’s imagine you land in Montreal on September 1st, sign a lease for an apartment, and start a new job on September 15th. For tax purposes, the CRA will likely consider you a Canadian tax resident from September 1st. This means that from that day forward, Canada expects you to report your worldwide income.
There are also instances of "deemed residents," which apply to certain individuals like those working for the Canadian government abroad, or specific types of visa holders who might be considered residents even if they don't have substantial ties. However, for the vast majority of expats and immigrants, it boils down to the date you physically arrive and set up your life here. This immediate start to your tax obligations is why it’s so vital to get your head around these rules right away, so you don't accidentally miss reporting something later on.
Specific Scenarios and How They're Taxed (or Not!)
Navigating the specifics of what is and isn't taxed when you bring money into Canada requires a good understanding of various scenarios. Let's break down some common situations that newcomers encounter.
Transferring Savings and Existing Assets
This is the big one for many, and it often comes with a huge sigh of relief once understood. As we touched on earlier, the funds you accumulated before becoming a Canadian tax resident are generally considered your capital and are not taxed when transferred into Canada. This includes:
- Cash savings: Money sitting in your bank accounts from prior earnings.
- Proceeds from property sales: If you sold a house, land, or other real estate in your home country before becoming a Canadian tax resident, that money is typically not taxed upon its arrival in Canada.
- Investment portfolios: The value of your investments (stocks, bonds, mutual funds) held abroad before you moved here. However, any new income generated from these investments after you become a tax resident will be taxable in Canada (more on this below).
- Pension lump sums: If you received a one-time payout from a pension scheme from a previous employer abroad before you moved, that capital is usually not taxed when you bring it in.
The key takeaway here is robust record-keeping. The CRA expects you to be able to prove that these funds were indeed your capital from before you became a tax resident. Keep statements from foreign banks, property sale agreements, investment account histories, and any documentation proving the origin and date of acquisition of these funds. It's your best defense if the CRA ever asks questions.
An important related point: if you hold foreign property (this can include real estate, bank accounts, investments, etc.) that costs CAD $100,000 or more at any point during the tax year, you generally have to report it to the CRA on Form T1135, Statement of Foreign Property. This is purely for informational purposes and doesn't mean your property is being taxed, but failing to file it can lead to hefty penalties. You'll find a lot more detailed information about this requirement in Understanding Reporting Foreign Property (T1135) in Canada.
Foreign Income Earned After Becoming a Resident
Here’s where it gets interesting – and where many newcomers can stumble. Once you become a Canadian tax resident, Canada expects you to report and pay tax on your worldwide income. This means any income earned anywhere in the world from that point forward is subject to Canadian income tax laws.
Let’s consider some common scenarios:
- Rental income from a property abroad: If you own a rental property in your home country and continue to receive rent after you become a Canadian tax resident, that rental income must be reported on your Canadian tax return.
- Foreign investment income: Dividends from stocks you hold in a foreign brokerage account, interest from foreign bank accounts, or capital gains from selling foreign investments after you become a Canadian tax resident are all taxable in Canada.
- Foreign pensions: If you receive regular pension payments from a foreign government or employer after you've established residency in Canada, these payments are generally taxable.
- Freelance or business income from abroad: Many newcomers continue to work remotely for foreign clients or run an online business. Any income generated from these activities after becoming a Canadian tax resident is considered Canadian income.
Now, before you panic about double taxation, Canada has measures in place to prevent this. It has tax treaties with many countries, and its domestic law provides for a foreign tax credit. This means if you paid tax on foreign income in another country, you can usually claim a credit for that foreign tax paid against the Canadian tax owing on the same income. This helps ensure you're not paying tax twice on the same dollar. Exploring Understanding Tax Treaties and Foreign Tax Credits in Canada is highly recommended for anyone with ongoing foreign income. For complex situations, particularly involving multiple income streams or assets abroad, consulting with a tax specialist like Taxes for Expats can provide invaluable peace of mind and ensure you're compliant without overpaying.
Gifts, Inheritances, and Loans from Abroad
Good news on this front! In Canada, genuine gifts (money or property received without expectation of repayment or goods/services in return) and inheritances (money or property received after someone's death) are generally not considered taxable income for the recipient. This holds true whether the gift or inheritance comes from within Canada or from abroad. So, if your parents send you a substantial gift to help with a down payment, or you inherit money from a relative overseas, that money usually won't be taxed when you receive it.
Similarly, bona fide loans from family members or institutions abroad are not considered income and therefore are not taxed. You’re simply receiving money that you intend to repay. However, if that loan generates interest (for instance, if you lend money to someone overseas and they pay you interest), that interest income would be taxable once you’re a Canadian tax resident. Again, documentation is key – keep clear records of any gifts, inheritances, or loan agreements.
Practicalities of Moving Money
Once you understand the tax implications, the next step is often the practical one: how do you actually get your money from point A (your home country) to point B (Canada)? This process involves more than just a simple transfer; it requires careful consideration of banking, fees, and record-keeping.
Banking and International Transfers
Transferring funds internationally can seem daunting, but there are numerous options available, each with its own advantages and disadvantages.
- Traditional Bank Wire Transfers: This is often the first method people think of. You can arrange a wire transfer through your bank in your home country to your Canadian bank account. While reliable, these transfers can sometimes be quite costly due to exchange rate markups and transfer fees. They can also take a few business days to process. Many newcomers find it relatively easy to How to Open a Bank Account at a Canadian Bank as a Newcomer shortly after arriving, which is essential for receiving these funds.
- Online Money Transfer Services: These services have become incredibly popular due to their competitive exchange rates and lower fees compared to traditional banks. Companies like Wise (formerly TransferWise) offer transparent pricing and often faster transfer times. They allow you to send money directly from your foreign bank account to your Canadian bank account with minimal fuss. Many expats swear by them for moving larger sums efficiently.
- Bank Drafts/Certified Cheques: For very large sums, some individuals opt for a bank draft or certified cheque from their foreign bank, which they then bring to Canada and deposit into their new Canadian account. This method can feel more secure than carrying large amounts of cash, but it still requires declaration at the border if the amount is CAD $10,000 or more.
- Carrying Cash: While possible, carrying large amounts of physical cash is generally not recommended due to security risks and the strict declaration requirements at the border. Remember, anything over CAD $10,000 must be declared to CBSA.
Before initiating any large transfer, compare exchange rates and fees across different providers. A seemingly small percentage difference can add up to a significant amount when dealing with large sums.
Record Keeping: Your Best Friend
I cannot stress this enough: keep meticulous records! This is perhaps the most important piece of advice for any newcomer dealing with finances across borders. The CRA operates on a self-assessment system, meaning they generally trust you to report accurately, but they also have the right to audit you. If they question the source of your funds or the timing of income, having clear, organized documentation will save you immense stress and potential penalties.
What kind of records should you keep?
- Bank statements: Both foreign and Canadian, showing the flow of funds.
- Sale agreements: Documents proving the sale of any property or assets in your home country, clearly stating the date of sale and the amount received.
- Investment statements: Showing the value of your portfolios before and after your move.
- Gift letters/inheritance documents: If you received a gift or inheritance, a letter from the giver or official inheritance documents will be invaluable.
- Loan agreements: Formal documents outlining any loans received.
- Border declarations: Keep a copy of any declaration forms you filled out when entering Canada with large sums of money.
- Correspondence with financial advisors or tax consultants: Especially if you sought professional advice on your move.
These records should be kept for at least six years, as per CRA recommendations. Having everything organized in a digital folder or a physical binder dedicated to your relocation finances will make your life significantly easier if the CRA ever comes knocking.
Summary of Taxability for Money and Assets Brought into Canada
To help clarify everything we’ve discussed, here’s a quick overview of what is generally taxable and non-taxable when you bring money or assets to Canada:
| Category | Tax Status in Canada for Newcomers | Key Considerations |
|---|---|---|
| Initial Capital/Savings | Generally NOT taxable. (e.g., funds from selling a foreign home, pre-existing savings, investments held before becoming a resident) | Must be verifiable as capital acquired before Canadian tax residency. Keep records! |
| Foreign Income (post-residency) | FULLY taxable. (e.g., rental income from foreign property, dividends from foreign stocks, business profits, foreign pensions received after becoming a resident) | Canada taxes worldwide income for residents. Claim foreign tax credits or use tax treaties to avoid double taxation. |
| Gifts | NOT taxable for the recipient. | Must be a genuine gift with no expectation of repayment or services. |
| Inheritances | NOT taxable for the recipient. | No inheritance tax in Canada at the federal level. |
| Loans from Abroad | NOT taxable for the recipient. | Must be a genuine loan with clear repayment terms. |
| Amounts > CAD $10,000 | NOT taxed upon declaration, but MUST be declared to CBSA. | Failure to declare can lead to fines, seizure, or other legal issues. |
| Foreign Property > $100,000 | NOT taxed upon reporting, but MUST be reported on Form T1135. | Informational filing only, but penalties apply for non-compliance. |
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute professional tax, legal, or financial advice. Canadian tax laws are complex and can change. Your specific situation may vary based on your personal circumstances, immigration status, province of residence, and the terms of any tax treaties between Canada and your country of origin. It is highly recommended to consult with a qualified Canadian tax professional or the Canada Revenue Agency (CRA) directly for advice tailored to your individual needs.