How Much Cash Can I Bring Into Canada?
Arriving in a new country, especially one as organized (and sometimes bureaucratic!) as Canada, can feel like a minefield of rules and regulations. You’ve likely sold possessions, transferred savings, and might be wondering, with a wad of cash in your pocket or a significant amount in your bank accounts, what the deal is with bringing money into the country. Don't worry, you’re not alone in feeling this initial confusion; it’s a perfectly normal concern for any newcomer trying to navigate Canada’s financial landscape. This guide will walk you through everything you need to know about declaring cash and monetary instruments when you arrive, ensuring a smooth entry and a peaceful start to your Canadian adventure.
The Essentials: Understanding Canada’s Cash Declaration Rules
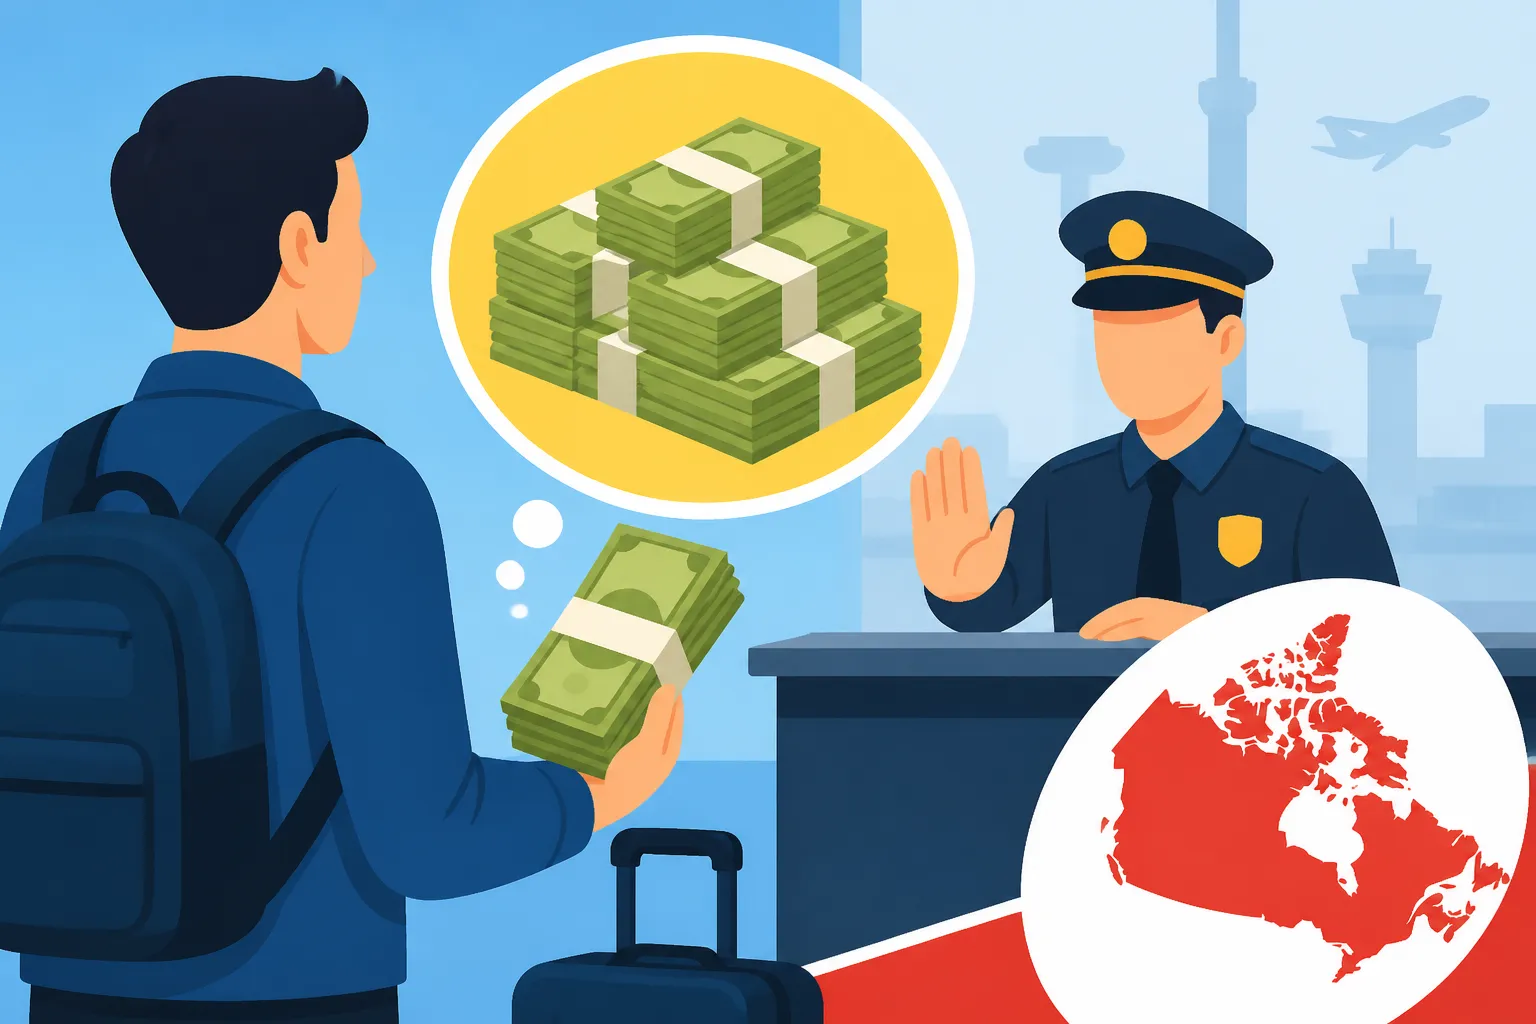
So, let's get straight to it: there isn't actually a hard limit on how much cash you can bring into Canada. That's right, you could technically arrive with a suitcase full of money. However, and this is a big however, there's a crucial reporting threshold you absolutely cannot ignore. If you arrive in Canada with $10,000 CAD or more, or its equivalent in foreign currency or monetary instruments, you must declare it to the Canada Border Services Agency (CBSA). This isn't about paying a tax on your money, but rather about transparency and regulatory compliance.
The $10,000 CAD Threshold: What You Need to Know
This $10,000 CAD figure is a cumulative amount. It includes all the cash you're carrying, whether it's Canadian dollars, US dollars, Euros, or any other currency. It also encompasses what are called "monetary instruments" – we'll dive into what those are in more detail shortly. The key is to add up everything you have. For instance, if you're carrying $5,000 USD and $3,000 CAD, you'll need to convert the USD to CAD to see if you cross that $10,000 mark. A quick mental calculation or using a currency exchange app on your phone before you land can save you a lot of headache.
This isn't just about what's in your wallet; it applies to money carried by everyone in your travel party. So, if you're a family of four and each person is carrying $3,000 CAD, that totals $12,000 CAD for the group, meaning you collectively exceed the threshold and must declare. The CBSA officer at the point of entry will ask you if you have $10,000 CAD or more. This is your cue to be honest and upfront. Trying to "split" the money among family members to stay under the individual limit is not how it works, and it could lead to serious issues.
The Declaration Process at the Border
When you arrive at a Canadian port of entry, whether by air, land, or sea, you'll go through customs. At this point, the CBSA officer will ask specific questions about what you're bringing into the country, and one of those questions will explicitly be about currency. If you have $10,000 CAD or more, you simply state that you do. You'll then be directed to fill out a form, which typically involves providing details about the amount of money, its origin, and its intended use. This might seem daunting, especially after a long flight, but remember, the officers are primarily there to ensure compliance, not to take your money.
The process is generally straightforward:
- Be Prepared: Know the total amount of cash and monetary instruments you (and your travelling companions) are carrying.
- Be Honest: When asked, declare the correct amount. There's no shame in having a lot of money; it's the failure to declare that causes problems.
- Fill Out the Form: You'll be given a form, often called the E677, "Report of Cross-Border Movement of Currency and Monetary Instruments." It will ask for your personal information, the types and amounts of currency/monetary instruments, and where the funds came from.
- Answer Questions: The officer might ask you a few questions to clarify the information on the form. This is usually to confirm the origin of funds and ensure it's not related to illicit activities. As long as your money is from legitimate sources – like savings, property sales, or inheritances – you'll be fine.
It's a good idea to have documentation supporting the origin of large sums, especially if you're bringing in a significant amount. This could include bank statements, property sale agreements, or letters from employers. While not always requested, having them on hand can speed up the process and provide peace of mind.
Why Canada Cares About Your Cash
You might be thinking, "It's my money, why does the government need to know how much I have?" This is a valid question, and it speaks to a larger global effort against financial crime. Canada, like many other developed nations, has strict regulations in place to protect its financial system.
Combating Money Laundering and Terrorism Financing
The primary reason for these declaration rules is to combat serious crimes like money laundering and the financing of terrorism. Large, undeclared sums of cash are often used by criminal organizations to move illicit funds across borders without detection. By requiring declarations, the CBSA can track significant cash movements and identify patterns that might indicate illegal activities. It helps law enforcement agencies piece together financial trails that could otherwise remain hidden.
For newcomers, it's essential to understand that this isn't a personal attack or suspicion aimed at you. It's a systemic measure. You're simply part of a larger net designed to catch criminals, and your honest declaration helps maintain the integrity of Canada's financial system. Canada takes its role in international anti-money laundering efforts very seriously, and this border declaration is a critical component of that.
Border Security and Economic Data Collection
Beyond preventing crime, these rules also serve broader border security purposes. Knowing what assets are entering the country helps the government maintain a clearer picture of cross-border financial flows. This data can be valuable for economic analysis and policy development, giving insights into how money moves into and out of Canada.
Think of it as part of Canada's overall strategy to maintain a secure and stable environment. It’s not just about goods and people, but also about the financial resources entering the country. For you, the honest newcomer, this means a few extra minutes at the border, but it contributes to the safety and security that likely drew you to Canada in the first place. You can learn more about how money moves in the country and its implications by reading about How the Canadian Tax System (CRA) Works: Federal and Provincial Explained (2027).
What Counts as "Cash" for Declaration Purposes?
This is where some newcomers get tripped up. It's not just about physical bills and coins. The definition of "currency and monetary instruments" under Canadian law is quite broad, and it’s important to understand the distinctions.
Currency: The Obvious Stuff
This is the straightforward part:
- Canadian currency: All Canadian banknotes and coins.
- Foreign currency: Banknotes and coins from any other country.
If you have $10,000 CAD equivalent or more in a mix of these physical currencies, you must declare it. This includes the dollars you might have exchanged at the airport or any money you still have from your home country.
Monetary Instruments: The Less Obvious Stuff
This is where it gets a bit more complex. Monetary instruments are essentially financial assets that can be easily converted to cash and transferred. They include:
- Traveller's cheques: While less common now, if you're carrying these, they count.
- Negotiable instruments: This is a broad category. It includes:
- Cheques, promissory notes, and money orders that are payable to the bearer (meaning anyone who holds them can cash them) or are signed without a payee's name (blank cheques, for instance).
- Drafts: Similar to cheques, these are orders to pay a specified sum to a specified person or bearer.
- Bonds, debentures, and stock certificates that are in bearer form.
So, if you're carrying a personal cheque made out to "cash" for $15,000, that needs to be declared. If you have a bank draft for the same amount, made out to you specifically, that also counts towards the threshold. The key differentiator for many of these is whether they are "bearer negotiable instruments" (BNIs) – meaning they can be transferred from person to person by mere delivery.
However, many common financial instruments are not included in this declaration requirement. For example, a personal cheque or money order made out specifically to your name or a specific entity (like a bank account) would generally not be considered a BNI for border declaration purposes, as it can't be freely transferred. Likewise, credit cards, debit cards, and funds held in your bank account accessible via these cards are not declared at the border. You're only declaring what you physically carry with you or your immediate travel party.
It's a subtle but significant difference. When you're thinking about your move and setting up your finances, you’ll be looking at options like opening a Canadian bank account. For advice on that, take a look at our guide on The Newcomer Guide to Opening a Bank Account in Canada. Many newcomers find that using services like Wise to transfer larger sums electronically is a much smoother process than carrying large amounts of physical cash or monetary instruments across borders, as electronic transfers don't fall under these physical declaration rules. It’s also often more secure and offers competitive exchange rates, allowing you to manage your funds before you even arrive.
Here’s a quick overview to help clarify:
| What to Declare (if total is $10,000 CAD or more) | What NOT to Declare (at the border) |
|---|---|
| Physical cash (Canadian and foreign banknotes/coins) | Funds in your bank accounts (Canadian or foreign) |
| Traveller's cheques | Credit cards |
| Bearer cheques (payable to "cash" or unsigned) | Debit cards |
| Bearer promissory notes, money orders, or drafts | Electronic fund transfers (e.g., through Wise, bank wire) |
| Bearer bonds, debentures, or stock certificates | Personal cheques or money orders made out to a specific payee |
The Consequences of Not Declaring
This is the part where you really want to pay attention. While the declaration process itself is straightforward, failing to declare can lead to some pretty serious headaches and financial penalties that no one wants to deal with when starting a new life in Canada.
Seizure and Penalties
If you're caught bringing $10,000 CAD or more into Canada and fail to declare it, the consequences can be immediate and severe. The CBSA officer has the authority to seize the entire amount of currency or monetary instruments. Yes, you read that right – your money could be taken from you. It's not just a portion; it's potentially the whole shebang.
Beyond seizure, you could face monetary penalties. These fines can be substantial, ranging from $250 CAD to $5,000 CAD, depending on the severity and circumstances of the non-declaration. Imagine losing a chunk of your savings, plus having to pay a hefty fine, all while trying to settle into a new country. It’s a stressful situation that is entirely avoidable by simply being honest at the border.
Furthermore, there might be a delay in processing your entry into Canada while the officers deal with the non-declaration, potentially holding you up for hours. This could throw a wrench into your carefully planned arrival, from missing connecting flights to delaying your ability to pick up keys for your new place.
Legal Ramifications and Impact on Future Status
The repercussions can extend beyond immediate financial penalties. Undeclared currency can be linked to other investigations, especially if the CBSA suspects illicit activities. While a simple oversight might not lead to criminal charges, a pattern of non-declaration or suspicion of money laundering could result in further investigations by financial intelligence units. This is why having documentation for large sums is prudent.
For newcomers, a run-in with the CBSA regarding non-declaration can also have implications for your immigration status. While a single, minor oversight might not jeopardize your permanent residency or work permit directly, any official record of non-compliance at the border could potentially be viewed negatively in future interactions with immigration authorities. For example, if you're trying to move from a temporary work permit to [Permanent Residence in Canada (2026)], having a clean record is always a good idea.
Moreover, if you intend to conduct any financial activities in Canada that involve these undeclared funds, such as depositing a large sum into a new bank account, the Canadian financial institutions have their own reporting obligations. They are required to report cash transactions over $10,000 CAD to FINTRAC (Financial Transactions and Reports Analysis Centre of Canada), Canada's financial intelligence unit. So, even if you manage to slip past the border without declaring, you'll still encounter reporting requirements once the money enters the Canadian financial system.
For those managing finances across borders, platforms like Wise offer a transparent way to transfer money directly into a Canadian bank account, which is typically much safer and less complicated than carrying large amounts of cash. When you're thinking about your overall financial situation in Canada, especially if you have assets abroad or income from foreign sources, consulting specialists like Taxes for Expats can provide valuable guidance on your tax obligations, especially if you have questions about Filing Your Tax Return with the CRA in Canada: The Complete Walkthrough (2027) with significant foreign assets. It's always best to be proactive and understand all your financial reporting duties from the outset.
Planning Your Finances as a Newcomer
Moving to Canada involves a lot of financial planning, and knowing how to handle your money upon arrival is just one piece of the puzzle. Beyond the border declaration, you'll want to think about how you'll access funds, pay bills, and manage your income.
Setting Up Your Canadian Bank Accounts
One of the first things you'll want to do after landing is to get your banking sorted. Opening a Canadian bank account is straightforward for newcomers, and having one makes managing your finances infinitely easier. You can often open an account with just your passport and immigration documents. It's crucial for receiving your salary, paying rent and utilities, and generally integrating into the Canadian economy. Check out our guide on What Documents Do I Need to Open a Bank Account in Canada? for a detailed checklist.
Once you have your account, you can transfer funds from your home country electronically. This is usually the safest and most efficient way to bring large sums of money into Canada. Services like Wise specialize in international money transfers, offering competitive exchange rates and lower fees compared to traditional banks. This avoids the need to carry physical cash and navigate border declarations for large amounts.
Understanding Your Tax Obligations
As a newcomer, you’ll also need to wrap your head around the Canadian tax system. Any income you earn in Canada will be subject to federal and provincial taxes. If you bring significant assets into Canada, or have investments abroad, these might have reporting implications. This is where understanding your Tax Residency in Canada: A Definitive Guide for Newcomers (2027) becomes critically important.
It’s not just about income tax; you’ll also need to apply for a How to Apply for a Social Insurance Number (SIN) in Canada, which is essential for working and accessing government benefits. For complex financial situations or questions about investments and foreign income, seeking advice from a tax professional specializing in expatriate finances, such as those at Taxes for Expats, can be incredibly beneficial. They can help you navigate Canadian tax laws, particularly if you have financial ties to other countries, ensuring you’re compliant from day one. Understanding your tax obligations is key to making Canada your long-term home, so don't delay in getting informed about How Much Income Tax Will I Pay in Canada in 2026?.
Budgeting and Cost of Living
Finally, beyond the initial transfer of funds, you’ll need a solid budget to manage your day-to-day expenses. Canada can be an expensive place, especially in major cities, so having a clear understanding of The Complete Guide to Cost of Living in Canada for Newcomers (2026) will be crucial. Factor in everything from rent and groceries to transportation and unexpected costs. Having access to your funds through a Canadian bank account and avoiding the stress of cash declarations will allow you to focus on what truly matters: building your new life here.
Disclaimer
The information provided in this article is for general guidance only and does not constitute legal or financial advice. While we strive to keep the information accurate and up-to-date, rules and regulations can change. It is always recommended to consult with the Canada Border Services Agency (CBSA) or a qualified legal/financial professional for advice tailored to your specific situation before making any decisions related to bringing cash or monetary instruments into Canada.